
Last updated: October 13, 2026
Quick Answer
Mortgage rates hitting 8% this year is not impossible, but it's also not the likely outcome. Freddie Mac's 30-year fixed average hit 7.40% for the week ending October 8, 2026, the highest in about 35 months, after climbing roughly a full percentage point since July [7][1]. Reaching 8% from the September average of 6.86% would require a jump so large it has only happened in about 4% of three-month stretches since 1972, according to Realtor.com senior economist Joel Berner [1]. The bigger threat to buyers right now isn't the headline rate. It's shrinking demand, price cuts hitting a four-year high, and lenders already pulling back.
Key Takeaways
- The 30-year fixed mortgage rate reached 7.40% the week of October 8, 2026, up from 6.30% a year earlier [7].
- Rates rose about one full percentage point between July 9 (6.49%) and October 8 (7.40%), 2026 [1].
- Reaching 8% from September's 6.86% average would be a top-4% move historically, per Realtor.com's Joel Berner [1].
- Pending home sales fell year over year in both August and September, before the latest spike even hit [7].
- 20.8% of active listings had a price cut in September 2026, the highest share in four years [10].
- Zillow projects the 30-year fixed rate at 7.1% by the end of 2026 and 6.5% by the end of 2027, not a sharp drop [3].
- A 1-percentage-point rate increase on a $400,000 mortgage adds roughly $250 to $270 to the monthly payment, depending on the loan term.
- Inventory remains about 16% below pre-pandemic norms even as some markets loosen up [3].
- Lenders are already cutting origination forecasts and weighing layoffs as demand softens, according to the Mortgage Bankers Association [6].
What Are Mortgage Rates Today, and How High Could They Go
The 30-year fixed mortgage rate stood at 7.40% for the week ending October 8, 2026, according to Freddie Mac's weekly survey, up from 7.28% a week earlier and a full percentage point above the 6.30% recorded a year prior [7]. That's the highest reading in roughly 35 months.
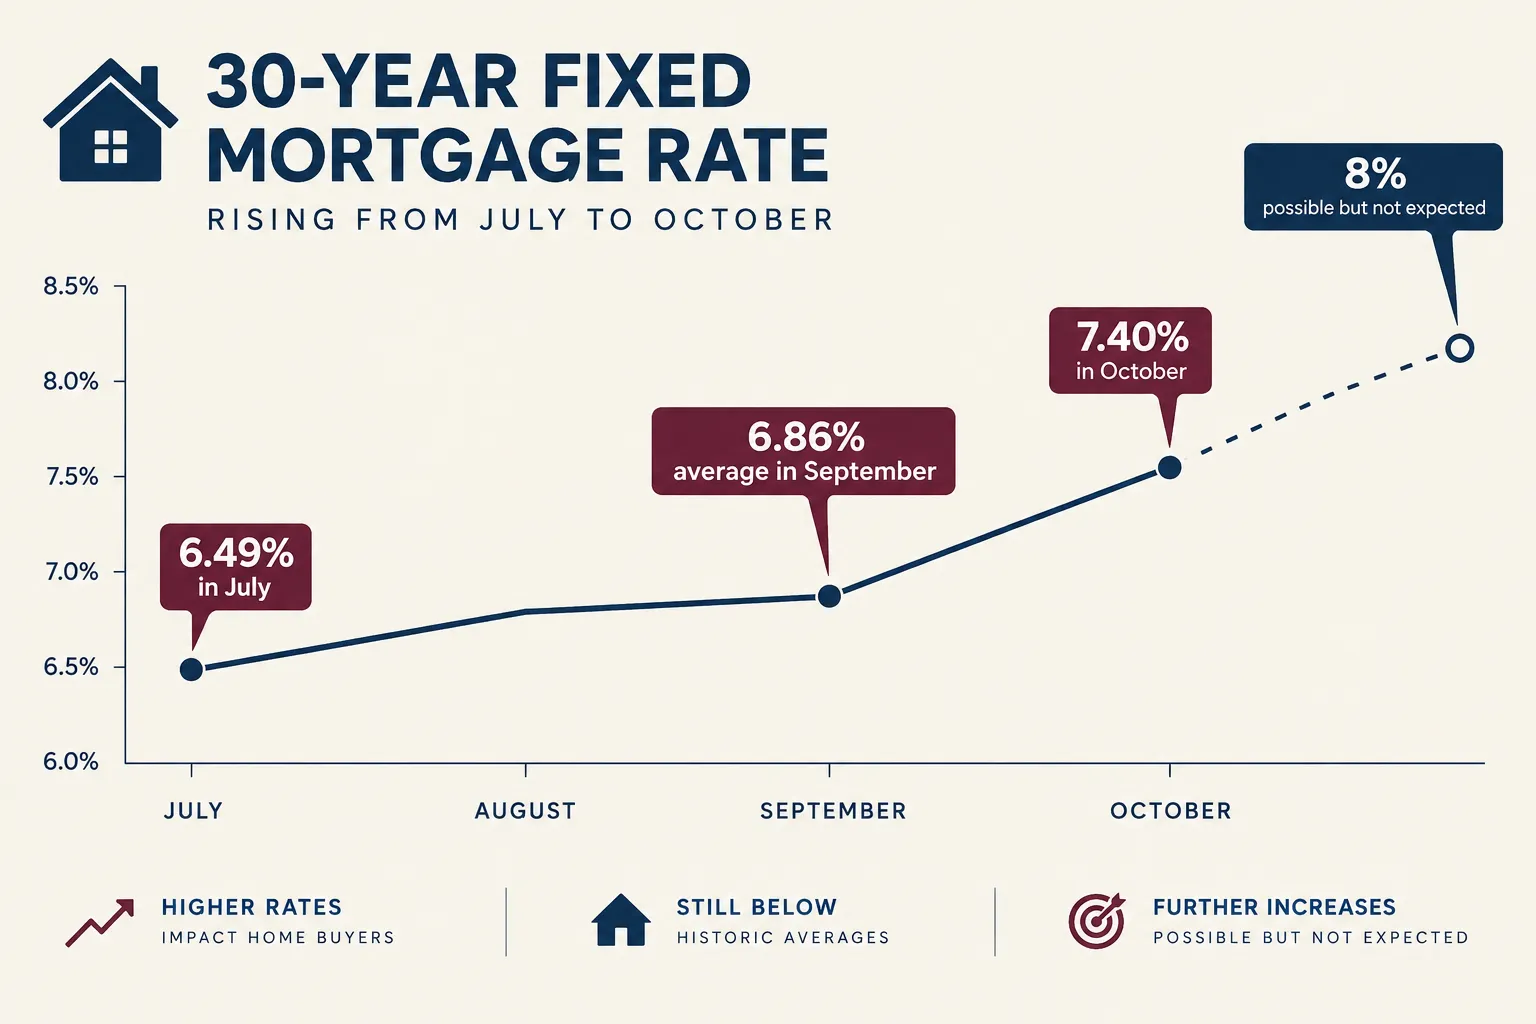
The climb has been fast by historical standards. Rates sat at 6.49% on July 9, 2026. Three months later, they were at 7.40% [1]. Fox Business and Yahoo Finance both flagged the same pattern in early October: a rapid run-up tied to bond-market pressure rather than a single Federal Reserve move [8][4].
How high rates could go depends mostly on the 10-year Treasury yield, which averaged 5.28% during the week Freddie Mac recorded that 7.40% print, and which briefly touched its highest level since 2002 [7]. Mortgage rates track Treasury yields closely because lenders price 30-year loans off that benchmark plus a risk margin. If the 10-year keeps climbing, 8% stops being a stretch. If it stabilizes, 7.1% to 7.4% is the more realistic band through year-end, per Zillow's forecast [3].
Why Are Mortgage Rates Increasing in 2026
Rates are climbing because of a bond-market squeeze, not because of one single policy decision. Inflation expectations, rising federal deficits, heavier Treasury issuance, and a broad bond sell-off have all pushed yields higher, and mortgage rates ride on the back of those yields [7].
Three forces are doing most of the work right now:
- Treasury supply. The federal government is issuing more debt, and when supply rises faster than demand, yields climb to attract buyers.
- Inflation expectations. Michael Wolf of Deloitte pointed to stronger inflation readings and solid payroll growth as reasons the Federal Reserve might hold rates tighter through year-end rather than cut them [1].
- A broad bond sell-off. When investors sell Treasuries, prices fall and yields rise, and mortgage rates rise with them [7].
Wolf's team at Deloitte still expects some relief, just not fast. Their outlook points to rate easing sometime before the end of 2027, not a quick reversal this year [1].
Can Mortgage Rates Hit 8% This Year
Yes, technically, but Realtor.com's own research treats an 8% rate by year-end as unlikely rather than expected. Joel Berner, senior economist at Realtor.com, said buyers shouldn't be overly concerned about an 8% rate materializing before December [1].
Here's the math behind that call. September's average sat at 6.86%. Getting to 8% would require a 1.14-percentage-point jump in roughly three months. Berner describes that kind of move as a "noteworthy run-up" rather than a baseline forecast, and he notes it has occurred in only about 4% of three-month periods going back to 1972 [1].
Decision rule: if you're waiting specifically for proof that 8% is coming before you act, you could be waiting on something that has a roughly 1-in-25 historical chance of happening in any given quarter. That's not zero. It's just not the way to bet your home search.
Mortgage Rates Hitting 8% This Year Is Not Impossible, and Yet, That Shouldn't Be Buyers' Biggest Concern
Mortgage rates hitting 8% this year is not impossible, given how fast rates moved from July to October 2026, but demand is already cracking at today's levels, and that's the part buyers are missing. Pending home sales fell year over year in both August and September, before the rate even cleared 7.3% [7]. Sellers noticed first.
By September, 20.8% of active listings carried a price cut, the highest share in four years [10]. That's not a market bracing for 8%. That's a market where buyers are already pulling back hard enough that sellers are discounting to get deals done. A rate headline grabs attention. A seller cutting price twice in six weeks is the actual signal worth watching.
What Should Home Buyers Focus on Besides Interest Rates
Buyers should weigh total monthly cost, negotiating leverage, and local inventory trends more heavily than the quoted rate alone. A rate is one input in a larger equation that includes price, taxes, insurance, HOA dues, and how much room you have to negotiate.
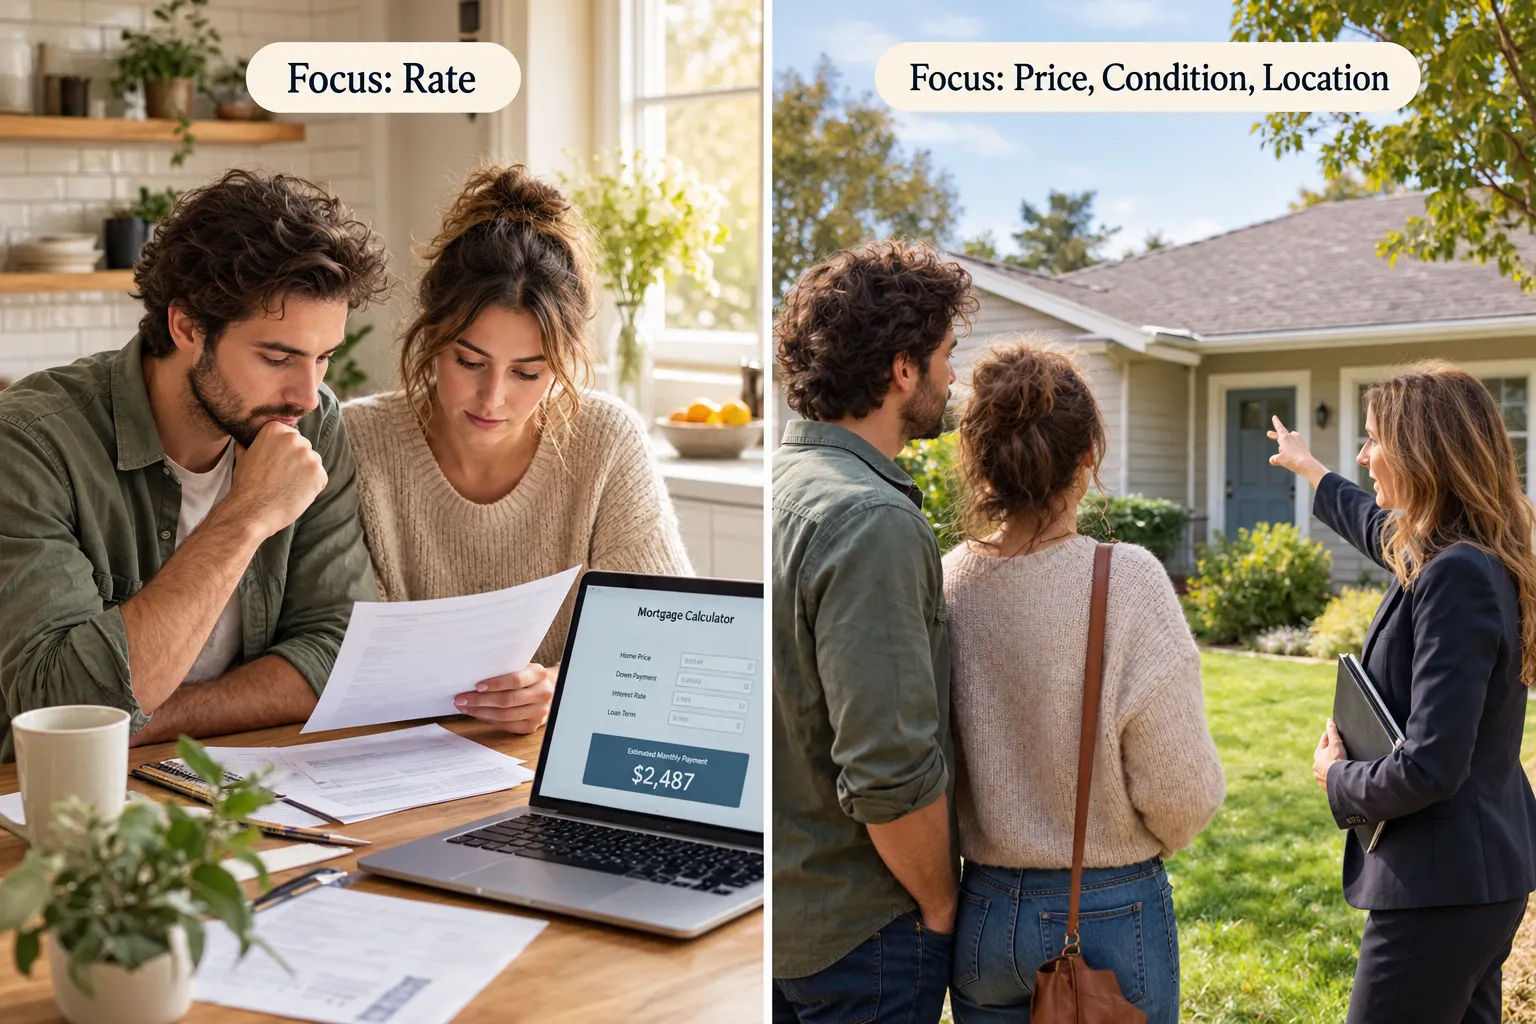
Watch these four things instead:
- Price flexibility in your target area. With 20.8% of listings taking a cut in September, buyers in many markets have real room to negotiate below asking [10].
- Local inventory. Zillow's October analysis shows inventory still running about 16% below pre-pandemic levels nationally, but Cotality's Chief Economist Selma Hepp points out the picture splits by region. Supply stays tight in the Midwest and Northeast, while parts of the Sunbelt and West Coast are seeing more construction and more buyer leverage [2][3].
- Lender health. The Mortgage Bankers Association's Bob Broeksmit flagged that affordability and borrower demand have weakened enough that some lenders are cutting origination forecasts or weighing layoffs [6]. A shaky lender mid-process is a real risk, not a footnote.
- Your own payment shock tolerance. Run the math on taxes and insurance increases, not just principal and interest.
Common mistake: chasing a lower rate quote from lender to lender while ignoring that the home itself is overpriced for the current market. A 0.25% rate difference rarely outweighs a $20,000 negotiation win on price.
How Much Does a 1% Increase in Mortgage Rates Affect Monthly Payments
A 1-percentage-point rate increase on a $400,000, 30-year fixed loan adds roughly $250 to $270 to the monthly payment, depending on the starting rate and loan balance. On a $300,000 loan, that same 1-point jump adds close to $190 to $200 a month.
| Loan amount | Rate move | Approximate monthly payment change |
|---|---|---|
| $300,000 | 6.86% to 7.86% | about +$195/month |
| $400,000 | 6.86% to 7.86% | about +$260/month |
| $500,000 | 6.86% to 7.86% | about +$325/month |
These are principal-and-interest estimates only; they don't include taxes, insurance, or HOA fees, which move the real number higher in most markets. Run your own numbers before assuming a specific figure applies to your loan size.
What's More Important: Mortgage Rate or Home Price When Buying
Price matters more than rate in most buying decisions, because price is fixed at closing while a rate can often be improved later through refinancing. A rate is rentable. A price is permanent until you sell.
That's why the price-cut data matters so much right now. If 20.8% of listings are already discounted, overpaying at today's rate to "lock in" a home is a worse trade than negotiating hard on price and accepting a higher rate you can refinance down the road. For a side-by-side on how local price trends are shifting, see our breakdown of how stalling home prices in 2026 are changing buyer tactics.
Choose price-first negotiating if: inventory in your target zip code has climbed and price cuts are common.
Choose rate-lock urgency if: you're in a tight, low-inventory market where sellers aren't budging on price at all.
Is It Better to Buy Now or Wait for Lower Mortgage Rates
Buying now can make sense if the home fits your budget at today's rate and you plan to refinance later, since waiting carries its own cost in the form of continued price appreciation or rent paid in the meantime. Waiting makes more sense only if your specific local market shows clear signs of softening, like rising price cuts or growing inventory.
Zillow's own forecast doesn't support waiting for a dramatic drop. The firm projects the 30-year fixed rate easing only to 7.1% by the end of 2026 and 6.5% by the end of 2027, a slow grind rather than a cliff dive [3]. Floor Covering Weekly's coverage of Zillow's October report describes the housing market entering an "early winter," meaning slower activity, not a rate collapse [5].
If you do decide to move now, understand how to lock in a mortgage rate before rates move again, and compare whether an adjustable structure makes sense given the current environment by reading our honest breakdown of adjustable rate mortgage pros and cons.
How Do Rising Mortgage Rates Affect Home Affordability, and How Do You Qualify Anyway
Rising rates reduce how much home your income qualifies for, because lenders calculate debt-to-income ratios using the monthly payment, not the loan balance. A higher rate pushes that monthly number up, which can shrink your approved loan amount even if your income hasn't changed.
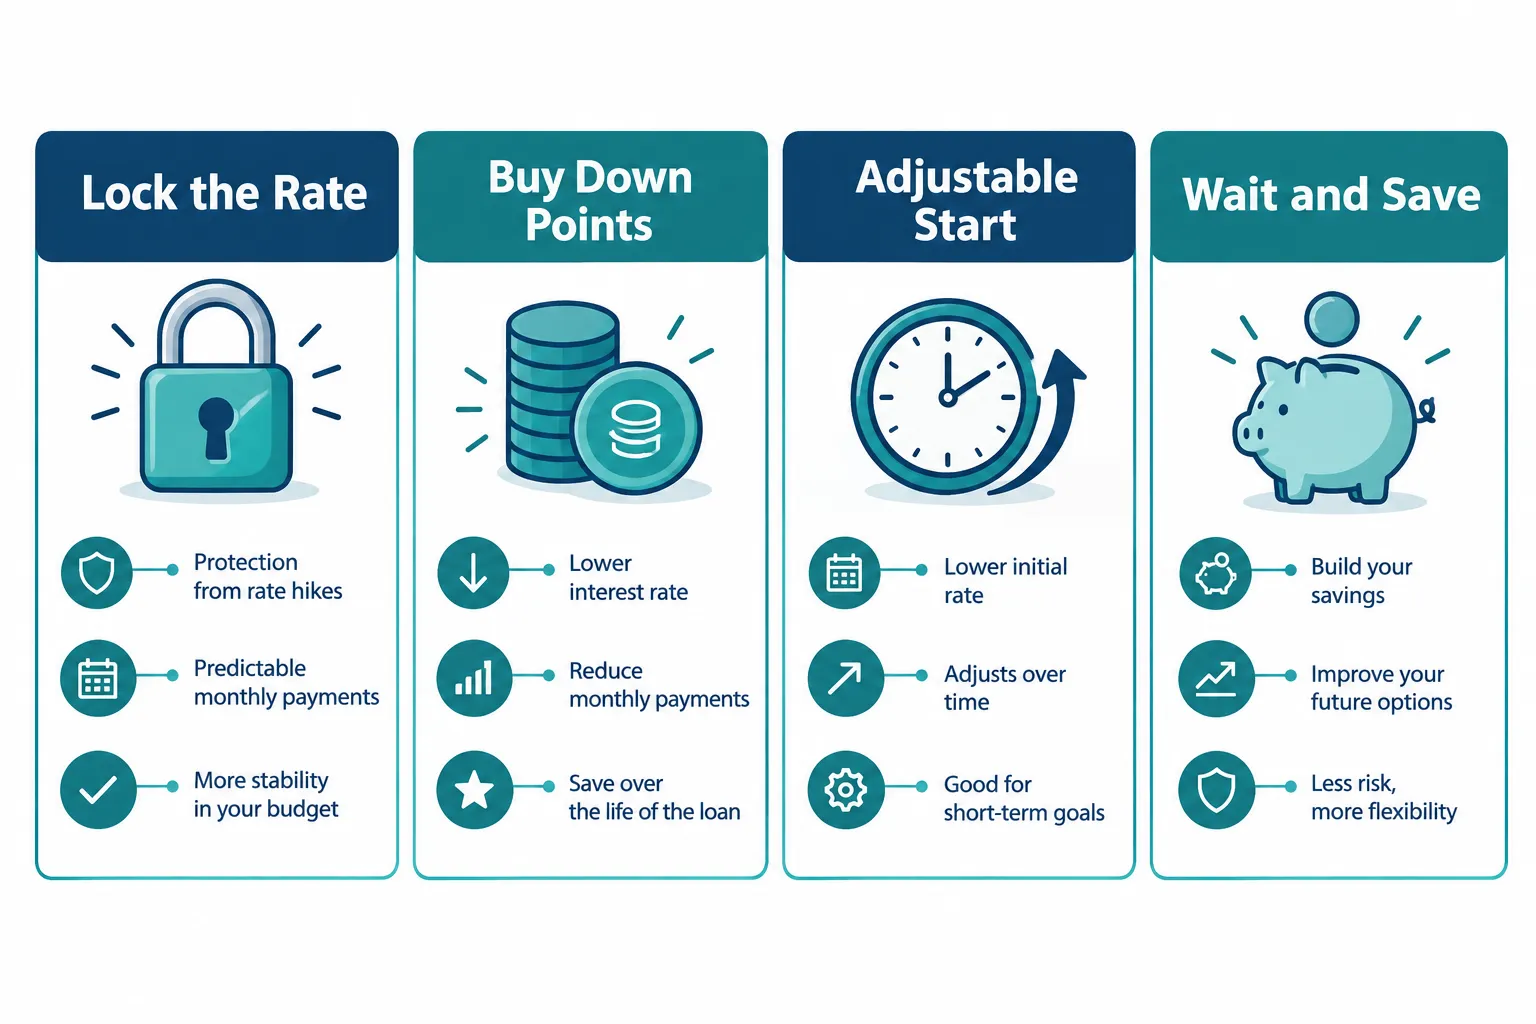
To qualify when rates sit near 7.4%:
- Pay down revolving debt first. Lowering your debt-to-income ratio before applying often does more than shopping for a slightly better rate.
- Consider a rate buydown. Paying points upfront to lower your rate can offset part of the monthly increase, especially if you plan to stay in the home for several years.
- Look at non-traditional loan products if your income is non-standard. Self-employed buyers and investors sometimes qualify more easily through non-QM mortgage lenders than through conventional underwriting.
- Cut your PMI exposure where possible. If you're financing above 80% loan-to-value, understand how PMI works and how to remove it early to reduce your effective monthly cost.
Edge case: buyers with strong credit but thin cash reserves sometimes qualify on paper but get squeezed at closing by rate locks expiring. Confirm your lender's lock period covers your full closing timeline before you commit.
What's the Difference Between Mortgage Rate and APR
The mortgage rate is the cost of borrowing applied to your loan balance each year. The APR, or annual percentage rate, includes the interest rate plus most lender fees, points, and closing costs, expressed as a single yearly percentage, so it's almost always higher than the quoted rate.
When comparing lenders, the rate tells you your monthly principal-and-interest cost. The APR tells you the true cost of the loan over its life, including the fees buried in the fine print. Always compare APR to APR across lenders, not rate to rate, because a lender advertising a lower rate can still have a higher APR once fees are added in.
Should You Refinance If Rates Drop After Reaching 8%
Refinancing makes sense if rates drop at least half a point to a full point below your current rate and you plan to stay in the home long enough to recoup closing costs, generally two to four years depending on loan size. If rates do spike toward 8% this year and later ease back toward Zillow's projected 7.1% to 6.5% range over the next year, that gap is often enough to justify a refinance for most loan balances [3].
Run the break-even math before committing: divide your total refinance closing costs by your monthly savings to find how many months it takes to come out ahead. If you're moving before that date, skip the refinance.
How to Lock in a Mortgage Rate Before Rates Go Up
Lock your rate once you have a signed purchase contract and a lender ready to process your loan, typically 30 to 60 days before your expected closing date. Locking too early risks the lock expiring before closing; locking too late risks the rate moving against you during the bond-market swings described earlier in this guide.
Ask your lender these three questions before locking:
- How many days does the lock last, and what happens if closing is delayed?
- Is there a float-down option if rates drop after I lock?
- What's the cost difference between locking now versus floating for two more weeks?
Given how fast rates moved from 6.49% to 7.40% between July and October 2026, floating and hoping for a better number has been a losing bet most of this year [1][7]. If you're already under contract and the numbers work, locking beats gambling.
Mortgage Rates Hitting 8% This Year Is Not Impossible, and Yet, That Shouldn't Be Buyers' Biggest Concern in a Softening Market
Even with rates near multi-year highs, the real stress point in 2026 is a market where buyers have pulled back faster than sellers have adjusted. Pending sales dropped year over year in August and September, price cuts hit a four-year high in September, and lenders are already trimming staff and origination forecasts in response [7][10][6].
That combination, not the rate headline, is what should shape your strategy. A buyer who understands whether they're operating in a buyers market or a sellers market right now has more leverage than a buyer who's simply refreshing rate-tracker websites. For a seasonal read on where leverage currently sits, see our analysis of whether fall 2026 favors buyers as sellers start to blink.
Frequently Asked Questions
Will mortgage rates hit 8% in 2026?
It's possible but not the expected outcome. Reaching 8% from September's 6.86% average would require a move that has only happened in about 4% of three-month periods since 1972, according to Realtor.com [1].
What's causing mortgage rates to rise right now?
A combination of rising Treasury yields, heavier government debt issuance, inflation expectations, and a broad bond sell-off, according to Realtor.com's research team [7].
Is 7.4% a high mortgage rate historically?
It's the highest reading in roughly 35 months as of October 2026, but it's not unprecedented compared to rates seen in the early 2000s [7].
Should I wait for rates to drop before buying a house?
Only if your local market shows real softening, like rising inventory or frequent price cuts. Zillow projects rates easing slowly to 7.1% by the end of 2026, not a sharp drop [3].
How much more will I pay per month if rates rise 1%?
On a $400,000 loan, expect roughly $250 to $270 more per month in principal and interest alone.
Is the mortgage rate or the APR the better number to compare lenders with?
APR, because it includes fees and points along with the rate, giving a truer picture of total borrowing cost.
Are lenders struggling right now?
Some are. The Mortgage Bankers Association's Bob Broeksmit said weakening demand has pushed some lenders to cut origination forecasts or consider layoffs [6].
What should first-time buyers prioritize over the interest rate?
Local price trends, debt-to-income ratio, and total monthly cost including taxes and insurance, since those factors often move your budget more than a quarter-point rate shift.
Conclusion
Mortgage rates climbed fast this year, from 6.49% in July to 7.40% in October, and an 8% headline isn't off the table before December [1][7]. But chasing or fearing that number while ignoring a market where pending sales are falling and one in five listings is already discounted means missing the leverage actually on the table [7][10].
Next steps: check how many homes in your target area have had a price cut in the last 30 days, get a real APR comparison from at least two lenders instead of comparing quoted rates alone, and decide your buy-now-versus-wait strategy based on local inventory data rather than national rate forecasts. The rate will move either way. Your negotiating position right now is the part you can actually control.
References
[1] Mortgage Rates 8 Percent 2026 Money Monday – https://www.realtor.com/advice/finance/mortgage-rates-8-percent-2026-money-monday/
[2] Us Home Price Insights October 2026 – https://www.cotality.com/insights/articles/us-home-price-insights-october-2026
[3] Mortgage Rate Trends – https://www.zillow.com/research/mortgage-rate-trends/
[4] Is 8 Next Why Mortgage Rates Have Surged And May Stay Higher For Longer – https://finance.yahoo.com/real-estate/article/is-8-next-why-mortgage-rates-have-surged-and-may-stay-higher-for-longer-163029048.html
[5] Zillow Report Shows Early Winter In Housing Market – https://www.floorcoveringweekly.com/main/topnews/zillow-report-shows-early-winter-in-housing-market-47166
[6] Mortgage Rates Lenders Pressure – https://www.housingwire.com/articles/mortgage-rates-lenders-pressure/
[7] Freddie Mac Mortgage Rates October 8 2026 – https://www.realtor.com/research/freddie-mac-mortgage-rates-october-8-2026/
[8] Mortgage Rates 10 8 2026 – https://www.foxbusiness.com/economy/mortgage-rates-10-8-2026
[9] Pending Sales Take A Hit As Mortgage Rates Sit At 7.5 – https://www.realestatenews.com/2026/10/06/pending-sales-take-a-hit-as-mortgage-rates-sit-at-7-5
[10] Mortgage Rates Today Fed Rate Hike October 1 2026 – https://www.realtor.com/news/trends/mortgage-rates-today-fed-rate-hike-october-1-2026/