
Last updated: October 4, 2026
Quick Answer
Mortgage rates crossed 7% in late September 2026 and kept climbing, hitting 7.28% by October 1, the highest weekly average since November 2023 [4]. How 7% mortgages are wrecking the home-buyer playbook comes down to three things: smaller loan amounts qualify, monthly payments jump hundreds of dollars for the same house, and the old strategy of "wait for rates to drop" no longer has a clear payoff date. Buyers who built their math around 2024-era rates need a new plan, not just patience.
Key Takeaways
- Freddie Mac's 30-year fixed average hit 7.03% on September 24, 2026, then 7.28% by October 1, the first time above 7% since January 2025 [4][5].
- Daily trackers showed rates as high as 7.60% in late September, well above the weekly Freddie Mac average [5].
- Pending home sales fell 4.1% year over year in September as buyers hesitated [3].
- 20.8% of active listings took a price cut in September, the highest share for that month since 2018 [3].
- Active inventory rose 5.5% year over year to more than 1.16 million homes, but new listings dropped 1.7% as sellers also pulled back [3].
- NAR's chief economist, Lawrence Yun, says buyers should treat 7% as the new normal for the near term [5].
- Analysts surveyed by Reuters raised their rate forecasts to roughly 6.60% and 6.52% over the following two quarters, up from earlier projections near 6.30% [2].
- Rate hikes are forcing sellers to lean on concessions, like closing-cost help and rate buydowns, instead of cutting list prices outright [8].
How 7% Mortgages Are Wrecking the Home-Buyer Playbook: What Changed This Fall
Rates did not drift up slowly. They jumped from 6.66% in late August to 7.03% by September 24, then to 7.28% within another week, a move Realtor.com compared to several months of normal rate swings packed into a handful of weeks [3][4]. That kind of speed is exactly why "wrecking" is the right word, not "pressuring" or "challenging." A buyer who ran their numbers in August and got pre-approved was working with a different market by the time they found a house in October.
Jeff Ostrowski, a housing analyst at Bankrate, points out that 7% is not some magic economic line. It is a psychological one [4]. Crossing it tells buyers and sellers the same story: borrowing costs are staying elevated, so everyone should act like it instead of waiting around for a number that might not show back up soon. That shift in mindset is the actual wrecking ball here. It is not the rate itself. It is what the rate does to confidence.
What a 7% Mortgage Rate Actually Does to Your Monthly Payment
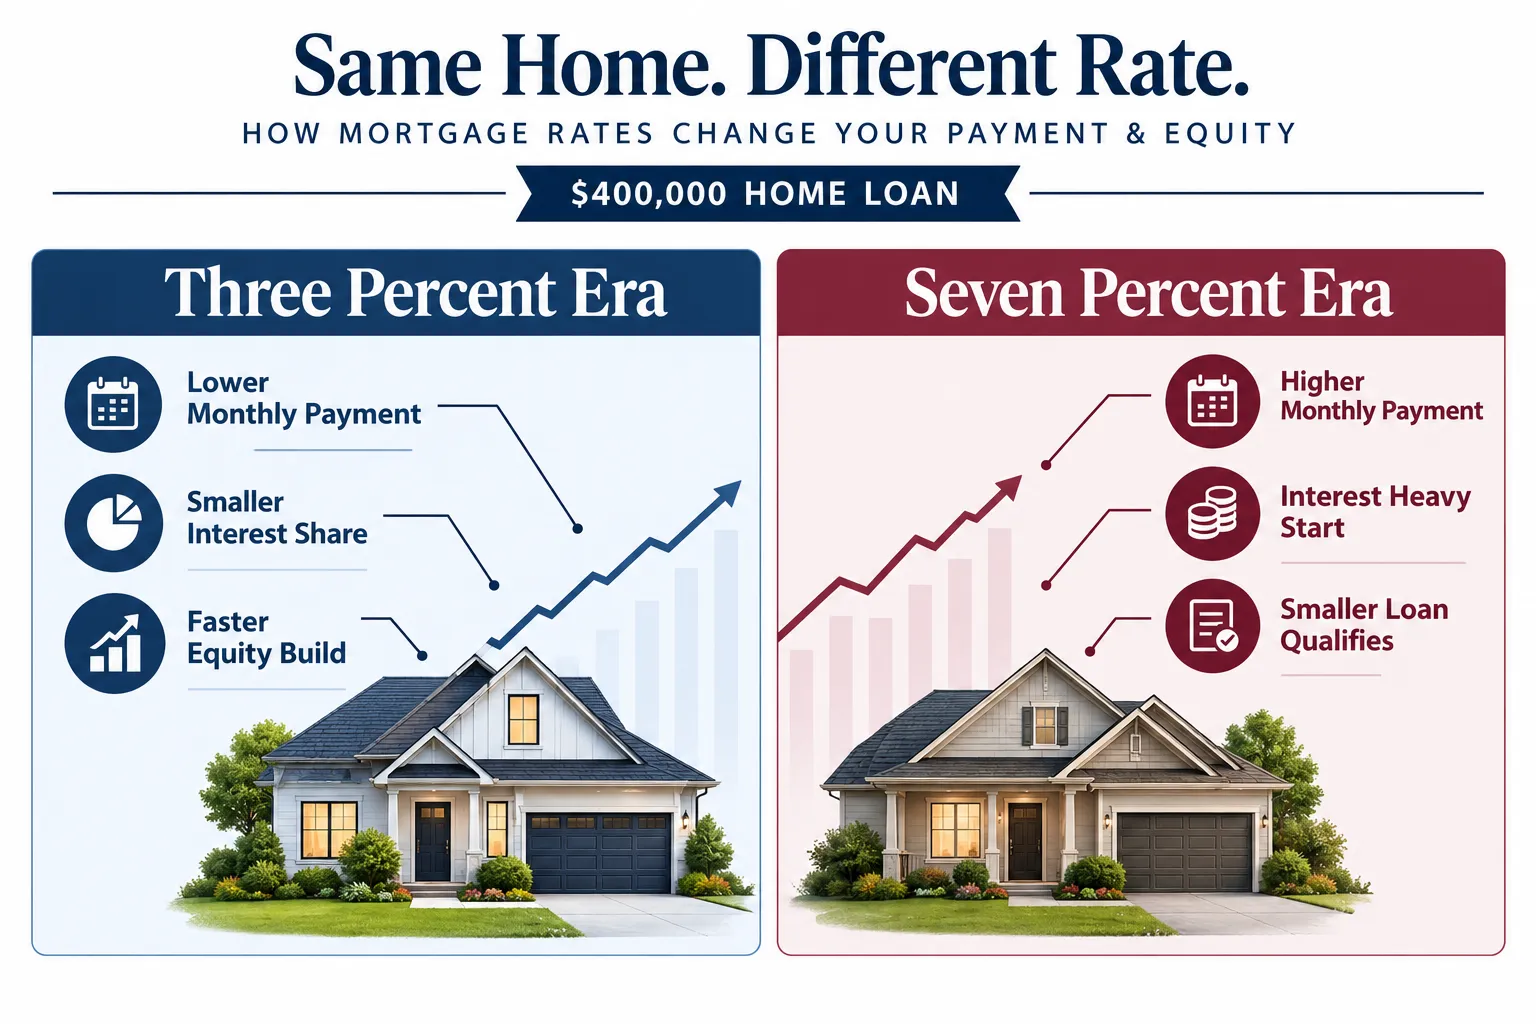
A 7% rate adds hundreds of dollars a month to the same loan compared to a 3% rate, and the gap grows the bigger the loan. On a $400,000 mortgage, dropping from 3% to 7% roughly doubles the monthly principal-and-interest payment, even though the home price never changed.
Here is the side-by-side math using a standard 30-year fixed loan on $400,000 borrowed:
| Rate | Estimated Monthly P&I | Total Interest Over 30 Years |
|---|---|---|
| 3% | About $1,686 | About $207,000 |
| 6% | About $2,398 | About $463,000 |
| 7% | About $2,661 | About $558,000 |
| 7.28% (early October 2026 average) | About $2,738 | About $586,000 |
These are standard amortization estimates, not quotes from a lender, and they exclude taxes, insurance, and HOA dues. Still, the pattern holds everywhere: every point above 6% adds roughly $260 to $280 a month on a $400,000 loan. That is a car payment, lost. For a family already stretching for a down payment, that gap is the whole playbook falling apart in one line item.
How Much House Can You Afford With 7% Interest Rates
At 7%, the same monthly budget buys a noticeably smaller house than it did at 6% or 3%, often 10% to 20% less purchasing power depending on the loan size. This is the single biggest reason buyers feel priced out even in markets where home values have not changed much.
A buyer comfortable with a $2,700 monthly payment could afford close to $400,000 at 7%. At 6%, that same payment stretches to around $445,000. At 3%, it reaches past $635,000. The house did not get smaller. The rate made the dollar weaker.
Quick affordability checklist for 2026:
- Add up gross monthly income, then keep total housing costs (principal, interest, taxes, insurance, HOA) under 28% to 36% of that number
- Run the math at the actual rate you're quoted, not a rate from a headline or a rate your cousin got in 2021
- Build in property tax and insurance increases, since premiums have risen sharply in several states
- Ask your lender for a payment estimate at 7% and at 6.5%, so you can see the real range before you shop
Why Did Mortgage Rates Jump to 7%, and What's the Average Rate Today
Rates climbed because bond markets repriced inflation and growth expectations faster than anyone forecasted going into fall 2026, pushing the 30-year fixed average to 7.28% by October 1, the highest weekly reading since November 2023 [4]. Freddie Mac's survey first showed 7.03% on September 24, the initial break above 7% since January 2025 [4][5].
Day-to-day rate trackers told an even sharper story. Mortgage News Daily logged a 7.60% 30-year rate on September 30, a reminder that Freddie Mac's weekly average and the rate a lender quotes on a Tuesday afternoon are not always the same number [5]. If a lender quotes something different from a headline you read online, ask which index and which date it's pulled from before you panic or celebrate.
Is 7% a Good Mortgage Rate Right Now?
Whether 7% counts as "good" depends entirely on the comparison point: it's high against the 3% rates of 2021, but it's in line with where Reuters-surveyed analysts now expect rates to hover for the next two quarters. That survey put average forecasts near 6.60% and 6.52%, up from earlier projections closer to 6.30% and 6.24% [2]. In other words, 7% is not a temporary spike economists expect to vanish by spring. It's closer to the floor than the ceiling right now.
Lawrence Yun of NAR has said plainly that buyers should get used to "7% as the new normal" until inflation and energy costs ease enough to pull rates down meaningfully [5]. That's not a comforting headline, but it is an honest one, and honest beats hopeful when you're about to sign a 30-year contract.
Decision rule: treat 7% as your real budget ceiling for the next six to twelve months. If a house only works at 6%, it's not a house that works right now. For a broader look at how rate stability (or the lack of it) is reshaping buyer strategy heading into 2026, see our breakdown of how stable 6% rates reshaped buyer and seller playbooks earlier this year.
How to Qualify for a Mortgage at 7% Interest, and Can You Negotiate the Rate
Qualifying at 7% requires a lower debt-to-income ratio, stronger credit, or a bigger down payment than qualifying did at 3%, since lenders are sizing your approved loan amount around today's higher monthly payment. Yes, you can negotiate your individual rate, even if you can't negotiate the market average.
Three negotiation levers that are genuinely available right now:
- Shop multiple lenders in a short window. Rate quotes vary by a quarter point or more between lenders on the same day, and applying with several within a two-week span counts as one credit inquiry for scoring purposes.
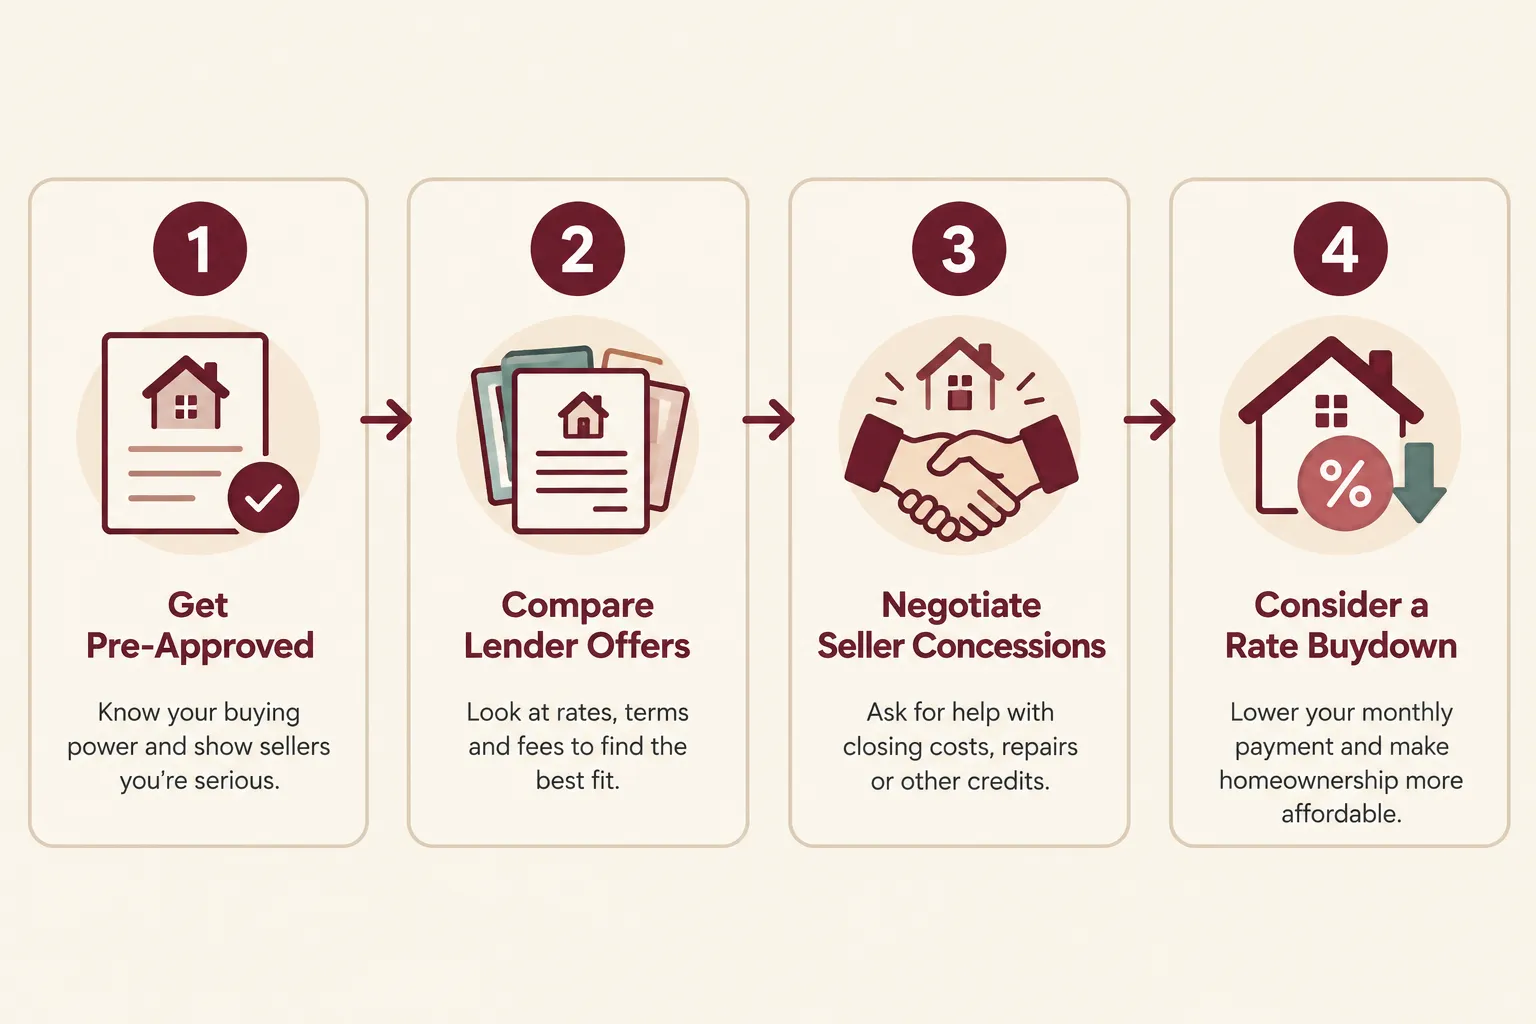
- Buy down the rate with points. Paying upfront to lower your rate can make sense if you plan to stay in the home 5+ years. Run the break-even math before paying for it.
- Ask the seller to cover part of a temporary buydown. With price cuts hitting 20.8% of listings in September, sellers have real motivation to offer concessions instead of slashing price outright [3][8].
Having impeccable credit and a documented, boring income history is the single biggest lever most buyers underestimate. Lenders reward predictability, not excitement. Getting pre-approved before you shop also tells sellers you're real money, not a tire-kicker. Our pre-approval guide walks through the documents to gather before you ever talk to a lender.
Should You Lock In a 7% Rate or Keep Shopping?
Lock in a rate once you're under contract and comfortable with the payment, because waiting to "see if it drops" has not paid off for most buyers in 2026 so far. Most lenders offer a float-down option for a small fee, which gives you partial protection either way.
Edge case: if your closing is more than 45 days out and your lender charges nothing for a float-down, locking early with that protection is usually the smarter move than gambling on timing the bottom. Common mistake: buyers who skip the lock entirely and float through underwriting, hoping for a dip, often end up locking late at a worse rate because they ran out of runway before closing.
How Rising Mortgage Rates Are Affecting Home Prices
Rates above 7% are not crashing home prices, but they are slowing the market and forcing sellers to compete harder for fewer serious buyers. Pending sales dropped 4.1% year over year in September, and nearly 21% of listings took a price cut, the highest September share since 2018 [3].
Sellers are adjusting behavior instead of list prices in many cases. Lisa Sturtevant, chief economist at Bright MLS, says higher rates have a chilling effect, and sellers increasingly need to offer closing-cost help or rate buydowns to keep buyers interested rather than dropping the sticker price [7][8]. Inventory climbed 5.5% year over year to more than 1.16 million active listings, but new listings fell 1.7%, meaning fewer sellers are even entering the market right now [3]. That's a landscape where buyers have slightly more choice but sellers who do list are getting more cautious about pricing. For a longer view on where prices head from here, our coverage of J.P. Morgan's outlook on stalling home prices lays out the tactics buyers are using to adjust.
First-Time Homebuyer Tips With High Mortgage Rates
First-time buyers should widen their search radius, get aggressive about seller concessions, and stop assuming a lower rate is coming soon enough to wait for it. The playbook that worked in 2021 is gate keeping buyers out of homes they could actually afford today if they adjusted their approach.
Fresh tactics worth trying in late 2026:
- Ask for a seller-paid rate buydown instead of (or in addition to) a price reduction
- Consider ARM products only if you have a concrete plan to refinance or sell within 5-7 years
- Look at homes with price cuts already baked in, since 20.8% of September listings had one [3]
- Check VA, FHA, and state down payment assistance before assuming conventional financing is your only option
If you're a veteran or active-duty buyer, our VA loan rules guide covers a financing path many first-timers skip. A broader walkthrough of the whole process lives in our first-time homebuyer guide, and GenZ buyers specifically should check our mortgage options breakdown built for younger buyers.
Is It Worth Refinancing an Old Mortgage at 7%?
Refinancing only makes sense right now if your current rate is above 7.28%, or if you need to pull cash out and the math still works after closing costs. Refinancing from a lower rate into today's 7%+ environment is, in almost every case, a step backward.
So based buyers sometimes confuse "refinancing" with "restructuring debt," and those are different moves. If you're carrying a high-interest second mortgage or credit card debt, a cash-out refinance at 7% might still beat the blended rate you're paying now. Run the actual numbers with a lender before assuming either direction is obviously right.
What Percentage of People Can Afford Homes at 7% Rates, and Should You Buy Now or Wait?
Affordability has tightened for a meaningful share of would-be buyers at 7%, which is exactly why pending sales fell 4.1% year over year in September and why first-time buyers are leaning harder on concessions and assistance programs [3]. There's no single national number for "percent who can afford a home," but the sales decline and the price-cut spike are the clearest real-time signals that the buyer pool has shrunk.
Should you buy now or wait? Let it cook before you see results is not bad advice for your savings account, but it's extraordinary bad advice for timing a purchase around a rate drop that Reuters-surveyed analysts don't expect to arrive soon [2]. If a house fits your budget at today's rate and you plan to stay 5+ years, buying now and refinancing later if rates drop usually beats waiting on a forecast. If the payment doesn't work at 7%, it's not the house for this year, and that's a fair, grown-up answer, not a failure.
If you're also weighing whether to hold onto a current property instead of selling into this market, our sell, stay, or rent it out guide walks through that math separately. And if negotiation feels intimidating at these rates, our negotiation power moves guide and our breakdown of the appraisal gap problem both cover scenarios buyers are hitting right now at these rate levels.
Frequently Asked Questions
What is the current average 30-year mortgage rate?
Freddie Mac reported 7.28% for the week ending October 1, 2026, the highest weekly average since November 2023 [4]. Daily lender quotes have run even higher, up to 7.60% on some trackers [5].
Why did mortgage rates suddenly jump to 7%?
Rates rose quickly in September 2026 as bond markets repriced inflation and economic growth expectations, pushing rates from 6.66% in late August to over 7% by September 24 and higher within another week [3][4].
How much more do I pay on a 7% mortgage versus a 3% mortgage?
On a $400,000 loan, moving from 3% to 7% roughly doubles the monthly principal-and-interest payment, adding close to $975 a month and hundreds of thousands in extra interest over 30 years.
Should I buy a house now or wait for rates to drop?
Buy now if the payment fits your budget at today's rate and you plan to stay 5+ years. Analysts surveyed by Reuters expect rates near 6.5% to 6.6% in coming quarters, not a return to 3% [2].
Can I negotiate my mortgage rate with a lender?
Yes. Shopping multiple lenders, paying for points, or asking the seller to fund a temporary buydown can all lower your effective rate, even when the market average stays high.
Is it worth refinancing an older mortgage at 7% right now?
Usually not, unless your current rate is already above 7.28% or you need cash out and the new blended cost still beats your current debt load after fees.
What percentage of buyers are affected by 7% rates?
There's no single verified national percentage, but pending home sales fell 4.1% year over year in September 2026, and 20.8% of listings took price cuts, both signs that a meaningful share of buyers have pulled back [3].
Is 7% considered a good mortgage rate in 2026?
It's high compared to 2021 but close to where forecasters expect rates to sit through 2027, which is why NAR's chief economist has called 7% the near-term normal [2][5].
Conclusion
How 7% mortgages are wrecking the home-buyer playbook really comes down to one shift: the old strategy of waiting out high rates has turned into a strategy of adjusting to them. Rates climbed from 6.66% to over 7.28% in roughly five weeks [3][4], pending sales slipped, and sellers started offering concessions instead of big price cuts [3][8]. None of that means the market is frozen. It means the rules changed.
Start by running your actual affordability numbers at today's rate, not last year's. Get pre-approved before you shop so you know your real ceiling. Ask about seller concessions and rate buydowns before assuming price is the only lever. And if the math doesn't work this year, that's useful information, not a dead end. Set a target rate and a target payment, then revisit both every quarter instead of checking rate headlines every day.
References
[1] Interest Rates Impact On Housing Market – https://www.usbank.com/investing/financial-perspectives/investing-insights/interest-rates-impact-on-housing-market.html
[2] High Mortgage Rates Keep Us Housing Market Revival Elusive 2026 09 15 – https://www.reuters.com/business/high-mortgage-rates-keep-us-housing-market-revival-elusive-2026-09-15/
[3] September 2026 Data – https://www.realtor.com/research/September-2026-data/
[4] Mortgage Rates Top 7 Reaching Highest Point Since February 2025 – https://themortgagepoint.com/2026/09/22/mortgage-rates-top-7-reaching-highest-point-since-february-2025/
[5] What 7 Rates Could Mean For Home Buyers – https://www.nar.realtor/news/real-estate-news/what-7-rates-could-mean-for-home-buyers
[6] Mortgage Rates 7 Percent Housing Affordability – https://fortune.com/2026/09/22/mortgage-rates-7-percent-housing-affordability/
[7] Mortgage Rates Freddie Mac Homebuying – https://www.npr.org/2026/09/24/nx-s1-5977796/mortgage-rates-freddie-mac-homebuying
[8] Mortgage Rates September 16 2026 – https://www.bankrate.com/mortgages/analysis/mortgage-rates-september-16-2026/
[9] Mortgage Rates 9 24 2026 – https://www.foxbusiness.com/economy/mortgage-rates-9-24-2026
[10] Interest Rates 30 Year Fixed October 2026 Moving Tips 20261001 – https://www.inquirer.com/real-estate/housing/interest-rates-30-year-fixed-october-2026-moving-tips-20261001.html